A hail damage roof insurance claim pays to repair or replace a roof that hail damaged, minus your deductible. You report the storm date to your insurer, an adjuster inspects the roof, and the insurer pays for the damage it agrees the storm caused. Many policies pay actual cash value first and the rest after the work is done.
We've re-roofed Upstate homes after hail, wind and Helene, and 30 of our Google reviews talk about the insurance side. Here's how a claim actually moves, with South Carolina's rules in it.
How does a hail damage roof insurance claim work?
Four people touch the claim: you, your insurer, the adjuster they send and, if you want one, a roofer. You report it, the adjuster inspects and writes an estimate, and the insurer pays what that estimate says, minus your deductible. If the roof gets replaced, a replacement cost policy usually pays in two checks.
That second check is the one people forget about. The first one arrives, and you stare at it the way you stare at a restaurant bill that seems short, wondering whether to say something. Say nothing yet. The rest is called recoverable depreciation, and it's waiting for your final invoice.
Here's the math the Tennessee Department of Commerce and Insurance uses for a five-year-old, $10,000 roof with a $1,000 deductible:
| What happens | Actual cash value policy | Replacement cost policy |
|---|---|---|
| Roof cost at claim time | Cash value: $10,000 | Replacement: $11,000 |
| Depreciation ($500 a year × 5) | Cash value: −$2,500, kept for good | Replacement: held back, then paid |
| Deductible | Cash value: −$1,000 | Replacement: −$1,000 |
| First check | Cash value: $6,500 | Replacement: $6,500 |
| Total paid | Cash value: $6,500 | Replacement: $10,000 |
Your declarations page tells you which column you're in. Look for "actual cash value" or "replacement cost" next to your dwelling coverage. It takes two minutes, and it's the most useful two minutes in this whole article (sorry to everything else I wrote).
Is it hail damage, or just an old roof?
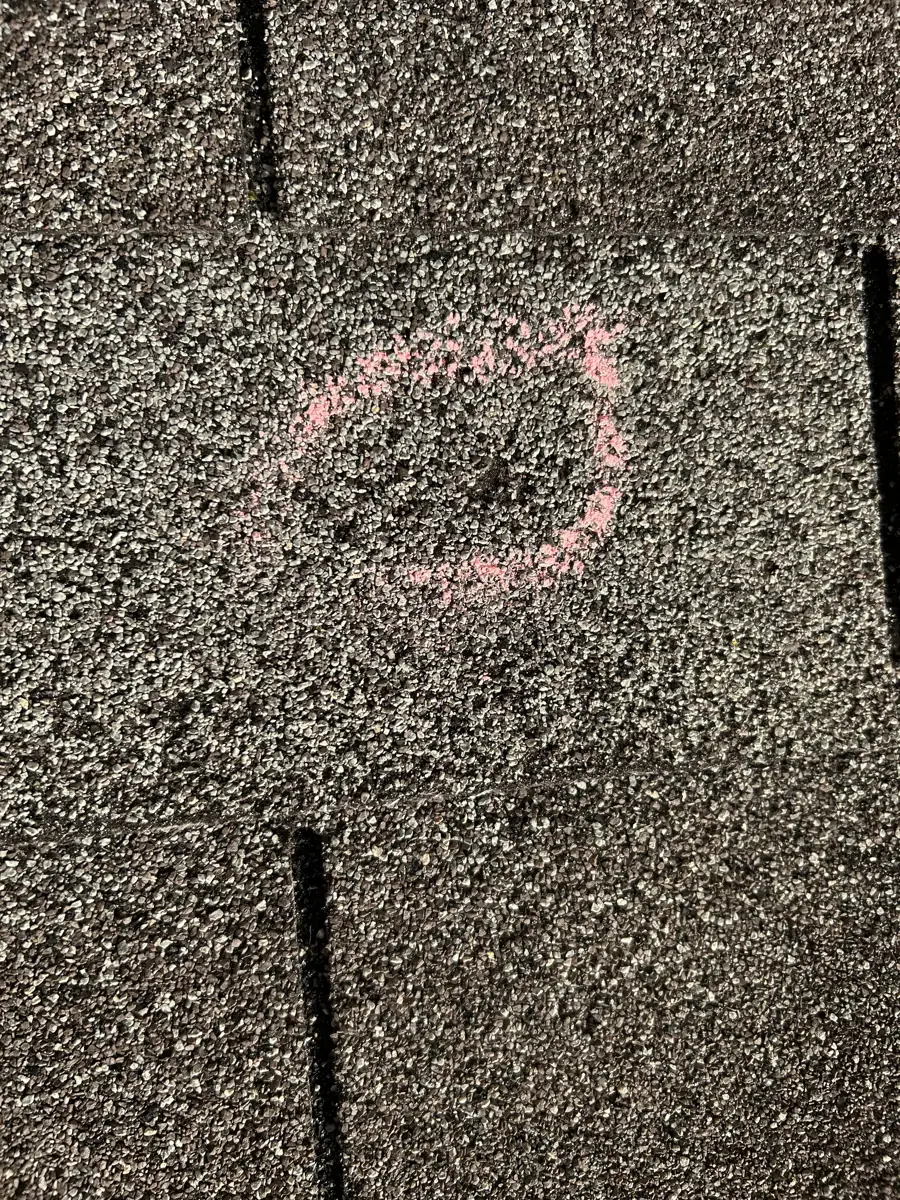
The Insurance Institute for Business & Home Safety lists three signs of hail on asphalt shingles: a random pattern of hits, bruises that feel soft when you press them, and cracks. Ridge caps take it worst. Dents on gutters, downspouts, flashing or the A/C unit back the story up.
- Random hits spread across a slope, not lined up along the edges
- Soft, bruised spots you can feel with a thumb
- Cracked or broken shingles, ridge caps first
- Fresh dents or spatter marks on gutters, vents and the A/C unit
What isn't hail, per the same guide: granules missing along the edges, even wear across the whole roof, factory defects and marks left by whoever installed it. Adjusters know that list by heart. Your gutters are the one witness on the property nobody can call old, and a fresh dent in a downspout is very hard to argue with.
Small hail counts too. A 2025 IBHS study found weathered shingles hit by hail under an inch were about ten times more likely to be damaged by a later big storm. The National Weather Service only calls hail severe at 1 inch, quarter size. Your roof doesn't read the weather service's memos.
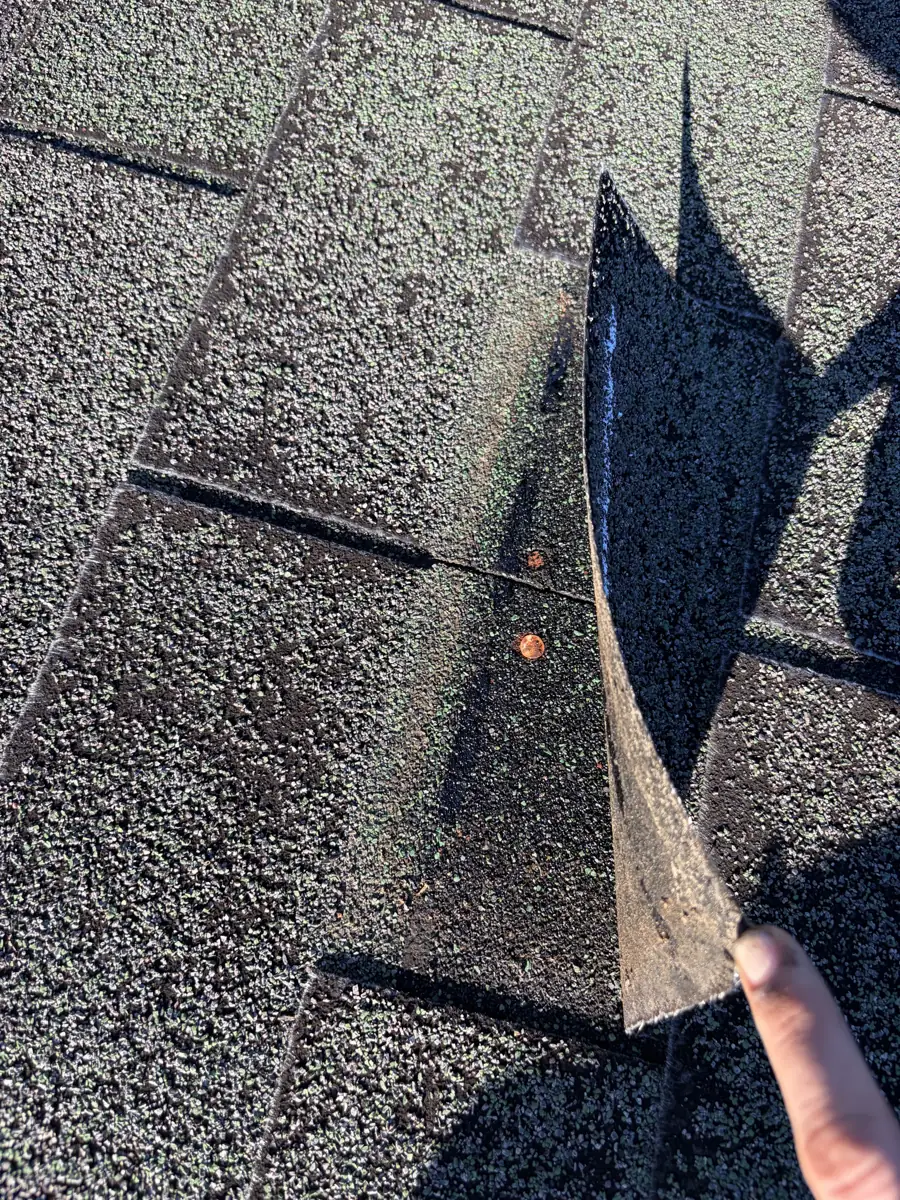
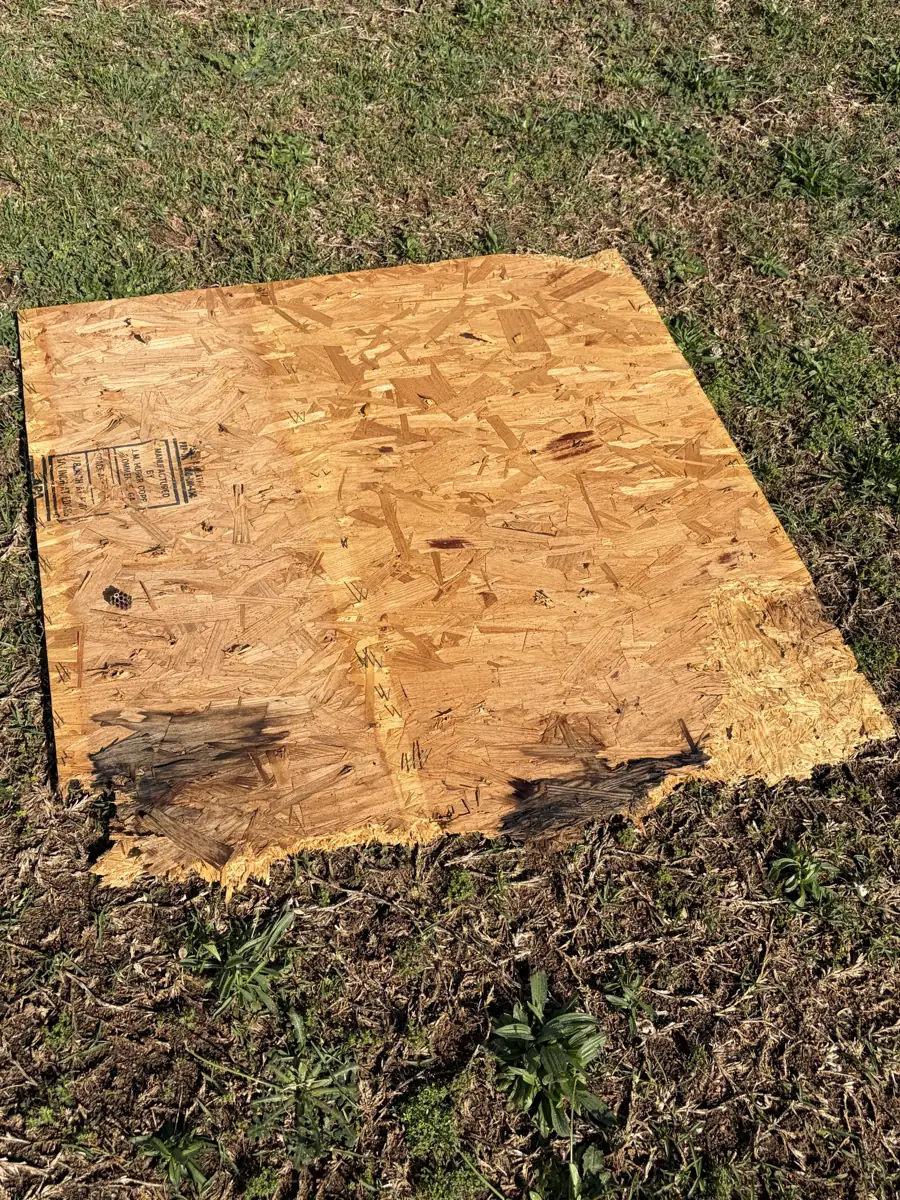
Left: lifting a tab during an inspection to see what's under it. Right: decking pulled during a tear-off, stained by a leak nobody saw from the ground.
How to file a roof insurance claim, step by step
File soon, and write the storm date down before you forget it. Many policies give about a year from the date of the storm, counted from the storm and not from the day you noticed. Your own policy's wording is the one that counts.
- Write down the storm date and time, then photograph the roof from the ground, plus the gutters, the A/C unit and any ceiling stains
- Stop more damage with a tarp if it's safe, and keep every receipt, since the NAIC says covered temporary repairs are usually reimbursed
- Call your insurer or start the claim online, and write down the claim number
- Record the adjuster's name, phone number and company, as the SC Department of Insurance tells homeowners to
- Get your own roof inspection before the adjuster visits, so you know what's up there
- Hold off on a full repair contract, because SCDOI advises contracting for nothing but temporary repairs until you and the adjuster agree
The photos matter more than they feel like they do. Nobody has ever looked back and thought, "I took too many pictures of my downspout." Take forty. The downspout won't mind, and it's about to become your star witness.
What happens when the adjuster comes out?
The adjuster walks the roof, marks a 10-by-10-foot test square on each slope and counts the hits inside it. That count and the photos drive the estimate. Each carrier sets its own internal threshold for when a slope gets replaced, and that number isn't in your policy.
One square can mislead. A Claims Journal analysis by a BRG consultant showed that zero hits in one square still fits a roof averaging three or four hits per 100 square feet, at 95% confidence. It recommends checking more squares, split by slope and shade.
In other words, your roof can fail a test it only sat one page of. It's like a teacher grading the first page of your exam and announcing your GPA to the class.
That's why it helps to have your roofer up there at the same visit, which a University of Missouri Extension piece recommends too. We'll come for the adjuster's visit and point out what we found, so nothing gets walked past.
"…was present for the adjuster and came back the day after the work was done to document the job and perform a final sweep for nails." Scott D., Google review, April 2026
Roof insurance claim denied? Here's what to do next
Ask for the denial reason in writing, then ask for a reinspection. Bring your own photos and a roofer's written findings. If it's still no, you can file a complaint with the SC Department of Insurance, which asks you to give the insurer a chance to fix it first.
- Wear and tear: the adjuster says it's age, not the storm
- Cosmetic only: some policies carry a cosmetic damage exclusion for dents that don't stop the roof keeping water out
- Under the deductible: the damage is real but costs less to fix than your deductible
- Reported late: the claim came in after the policy's deadline
If the insurer agrees there's damage but you disagree on the amount, many policies have an appraisal clause, where each side picks an appraiser. Courts have held that appraisal settles the amount, not whether something's covered. Read your policy before you reach for it.
South Carolina gives you one more protection. Under S.C. Code § 40-59-25, if you signed a roofing contract to be paid by insurance and the claim is denied in whole or part, you can cancel before midnight on the fifth business day after you get the written denial.
A denial letter has a way of arriving on a Friday afternoon, in a font picked to feel final. It isn't always final. Reinspections do overturn denials, usually when somebody brings better photos than the first visit got.
What South Carolina's H.4817 would change
H.4817 would bar licensed contractors in South Carolina from representing or negotiating a homeowner's roofing insurance claim. It would also ban advertising or promising to pay or rebate your deductible. It passed the House 96-17 on 1 April 2026 and was still in the Senate on 22 October 2026, so it isn't law yet.
For you, it means the claim is between you and your insurer, which is true today too. A roofer can inspect, document the damage, write up the work and be there when the adjuster comes. Anyone offering to "take care of" your deductible is offering something the bill would make illegal.
The FTC's storm-scam advice is short: walk away from anyone who wants cash up front or won't show a license, insurance and a written contract. And a "today only" price that expires before your adjuster can even visit is selling you the deadline, not the roof.
What we see on Upstate roofs after a storm
The pattern in our reviews is steady: a roof gets approved after a second look, and the wait in between is the hard part. 30 of our 94 written Google reviews mention insurance, adjusters or claims.
"They worked with our insurance carrier (SF) that tried to deny the claim." Theodore D., Google review, March 2026
That same roof, a large two-story, went on in a single day once the claim was approved. Another family waited out a wind and hail claim with leaks. In James W.'s words, "they stuck with us through the time it took to settle with our insurance by providing tarps to cover the leaks and replacing them as needed."
Upstate hail peaks in late spring and early summer. In May 2023, Greenville County got hail up to hen-egg size, the first that big since April 2020. Hen-egg is a size that should only ever appear in a recipe.
It adds up. State Farm alone paid about $109 million in South Carolina hail claims in 2024. Nationally, wind and hail made up 42.5% of homeowners insurance losses in 2023.
Hail damage roof claim FAQ
Does homeowners insurance cover hail damage to a roof?
Most standard homeowners policies cover sudden hail damage, minus your deductible. Some add a cosmetic damage exclusion or a separate wind/hail deductible, so check your declarations page. Normal wear and tear isn't covered.
How long do I have to file a hail damage claim?
It depends on your policy. Many allow about one year from the date of the storm, and the clock starts at the storm, not when you noticed. File as soon as you can.
What is a wind/hail deductible?
It's a separate deductible for wind or hail losses, often a percentage of your dwelling coverage instead of a flat amount. On a $300,000 dwelling limit, 2% is $6,000. South Carolina requires insurers to disclose it on your policy.
Can a roofer pay my deductible?
No, and you shouldn't want one to. You pay your deductible. South Carolina's H.4817 would ban roofers from advertising or promising to pay or rebate it.
Should I sign a roofing contract before the adjuster comes?
Not for the full repair. SCDOI advises contracting only for temporary repairs until you and the adjuster agree. If you've signed one and the claim is denied, S.C. Code § 40-59-25 lets you cancel by midnight on the fifth business day after the written denial.
What can I do if my roof claim is denied?
Ask for the reason in writing, then request a reinspection with new photos and a roofer's findings. If you only disagree on the amount, check your policy's appraisal clause. You can also call the SC Department of Insurance at 803-737-6160.
Get the roof looked at before the adjuster does
If you think hail got your roof, start with a free inspection from our storm damage roofing team. We'll show you what we found, photo by photo, and we can be there when your adjuster visits. Only want the inspection? Our free roof inspection page explains what we check.
How long it takes: Filing takes minutes. Most of the wait sits between the adjuster's visit and approval. Once it's approved, many of our roofs go on in a day.
What it costs: Your deductible, on an approved claim. Our roof inspection is free.
When to call us: After hail of quarter size or bigger, or when you spot fresh dents on gutters, vents or the A/C unit.
Not sure it's hail? We'll check.
Free roof inspection, with photos of everything we find.
Book my free inspection (864) 844-7777
Roofing, decks, exteriors and remodels across Greenville and the Upstate. 5.0 from 106 Google reviews.